The Freelancer's Financial Survival Guide
Health Insurance, Retirement, and Taxes When Your W2 Disappears
Bridge health insurance immediately with COBRA, a spouse's plan, or an ACA marketplace plan, and budget for premiums that can run $400–$700 a month for a single adult. Open a SEP-IRA or Solo 401(k) within your first tax year so you can still shelter up to 20–25 percent of net self-employment income for retirement. Set aside 25–30 percent of every payment you receive into a separate tax account to cover self-employment tax and quarterly estimated payments. Do these three things in the first 60 days and the scariest gaps are already closed.
Get the guide — freeWhat's inside
Plus 2 fill-in worksheets and a 12-step action checklist.
A page from the guide
Who it's for
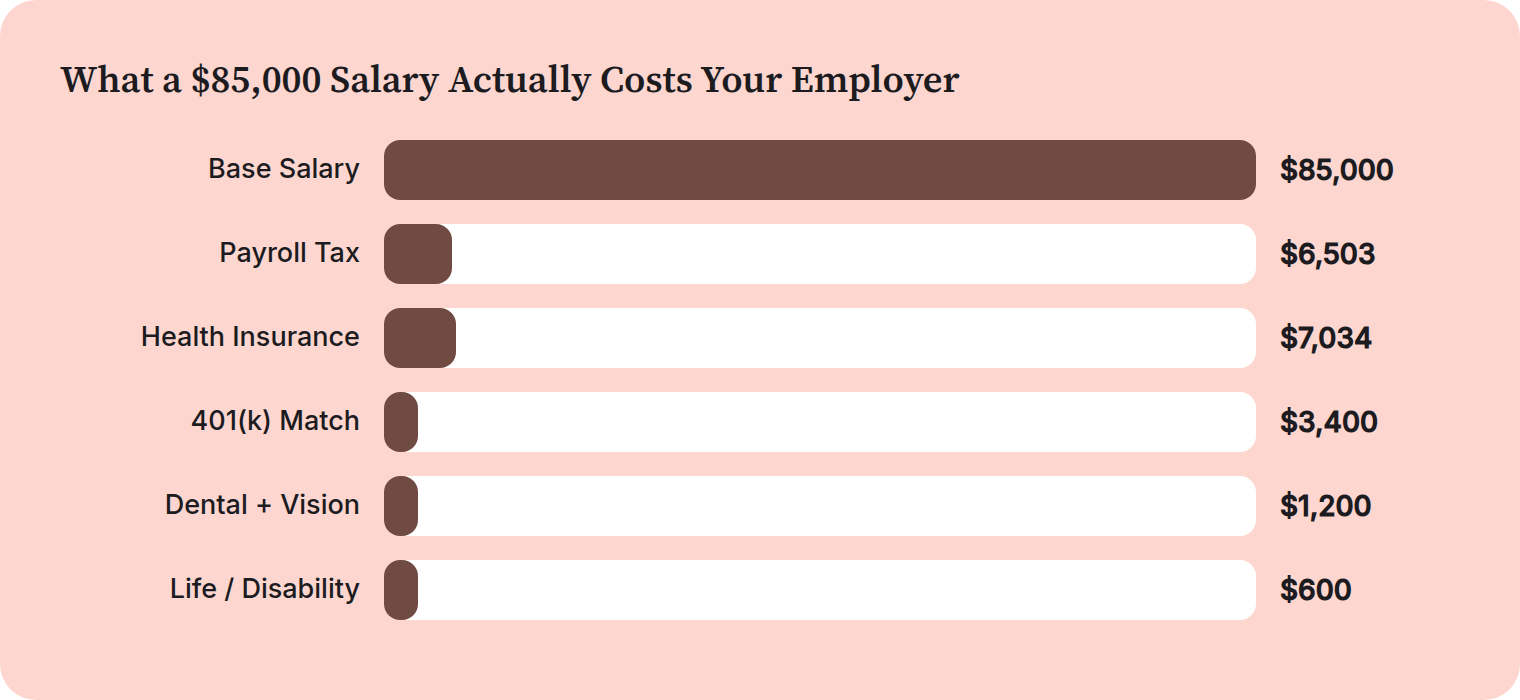
A salaried employee in their 30s or 40s who has lined up enough freelance clients to quit their job but is terrified of the financial gaps that come the day their W2 stops. They are days or weeks away from resigning and suddenly realize their employer has been quietly handling health insurance premiums, 401(k) matches, and payroll taxes on their behalf. They are not broke, but they have never had to price their own benefits or pay quarterly taxes before, and they are afraid that one wrong move will leave them uninsured, underfunded for retirement, or hit with a surprise IRS bill that wrecks the first year of freelancing.